

Cash Advance – Quick Borrow
TIMECORE Studio
- 4.7
- 26.00 Reviews
- 10.00K
- Downloads
- Free
- Price
Screenshots
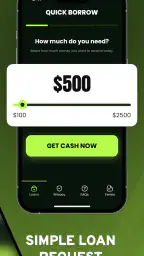
Cash Advance – Quick Borrow Pros and Cons
Pros
- Fast application process with minimal paperwork
- Clear repayment schedule helps users plan their budget
- Useful for handling unexpected short-term expenses
- Application is simple to navigate for new borrowers
- Loan decisions may be available outside traditional bank hours
Cons
- High fees or interest may make borrowing expensive
- Short repayment periods can create budget pressure
- Approval and loan terms may vary by applicant
- Late payments could lead to additional charges
- Availability and terms may depend on your location
 Analysis by All-app
Cash Advance – Quick Borrow is a finance app from TIMECORE Studio that I would approach as a practical borrowing starting point rather than a complete money-management system. Its purpose is straightforward: it helps users explore cash advance and personal loan offers through an online request. That narrow focus can be useful when an unexpected bill appears, but it also means the app deserves a more careful look than its simple store summary might suggest.
I spent time considering how it fits into real financial routines, not just how quickly someone can open a request. A borrowing app can feel helpful during the first few minutes and become less useful once the immediate problem has passed. The important question is whether it remains worth keeping installed, whether it encourages sensible decisions, and whether its process is clear enough for someone who is already under financial pressure.
What the first week feels like
The initial appeal is easy to understand. When money is tight, most people do not want a complicated financial dashboard filled with investment tools, budgeting charts, or account-management features. They want to see whether a borrowing option may be available and what they need to do next. This app is aimed at that moment, making it more focused than a general-purpose personal finance app.
In everyday use, I would see it as something to open when a short-term expense cannot comfortably wait until payday. Imagine a car repair, a utility bill, or an urgent household purchase arriving at the wrong time. The app may give you a route to request cash advance or personal loan offers online, which is more convenient than visiting several lenders separately. That convenience is its strongest first impression.
Still, convenience should not be confused with affordability. A request process can help you find an offer, but the offer itself may include costs, repayment conditions, and eligibility requirements that matter far more than the speed of the application. My advice is to treat the first week as an information-gathering period. Read every displayed term carefully, note the total repayment amount, and avoid accepting anything simply because the request feels quick.
The app is free to install, which removes an obvious barrier to trying it. That does not mean borrowing through it is free. Those are two completely different questions, and I would keep them separate from the beginning. The sensible workflow is to install the app only when you have a defined need, compare the result with other options, and decide based on the full cost rather than the amount offered.
Its audience is broad in terms of age because the content rating is Everyone, but financial responsibility is a different matter from age suitability. I would not recommend handing the decision to someone who has not understood repayment timing, fees, or the consequences of missing a payment. The friendly presentation of a finance app should never replace a written review of the agreement.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
The current release is version 1.0.7, and that places the product in an early stage of its life. I like seeing an app receive updates, but an early version also makes me more attentive to small points of friction: unclear wording, incomplete explanations, or a process that feels less polished than a mature banking application. I would keep the app updated before submitting anything important and reread the screens after an update, since financial workflows should not be treated casually.
A realistic emergency-money workflow
Suppose I had a necessary expense due within a few days and wanted to explore borrowing. I would first write down the exact amount needed and the date on which I could realistically repay it. Then I would use Cash Advance – Quick Borrow to review the available route, but I would not enter a larger request just because a larger figure appeared possible. Borrowing more than the original problem requires is one of the easiest ways for a short-term fix to become a longer-term burden.
Before proceeding, I would compare the app’s result with my bank’s overdraft terms, a credit-union option, a payment plan from the bill provider, or a trusted personal alternative. These options may be slower or less convenient, but they can sometimes be cheaper. The app earns its place in that process by helping me investigate, not by making the final decision for me.
A useful habit is to take notes while reviewing an offer rather than relying on memory. I would record the amount received, the total amount to repay, the repayment date, and any consequences associated with delay. This simple step is especially valuable when several offers look similar. The lowest requested amount is not automatically the best choice if its repayment schedule is harder to manage.
Where it differs from ordinary finance apps
Compared with budgeting apps, this product is much more transactional. A budgeting tool helps me monitor spending, plan ahead, and reduce the chance of needing emergency credit. Cash Advance – Quick Borrow is aimed at the point where I am already considering borrowing. That makes it more relevant during a cash shortage, but less useful as a daily financial companion.
Compared with a bank’s own borrowing service, the app may feel more convenient for exploring possibilities beyond one institution. A bank application can be better when I already have an established relationship, because account history and repayment arrangements may be easier to understand in one place. On the other hand, a dedicated offer-search experience can be useful when I want to investigate rather than commit immediately to my usual provider.
Compared with visiting lenders individually, an online request saves time and reduces repeated legwork. The trade-off is that digital convenience can make the process feel less serious than it is. I would deliberately slow down at the final decision stage. The app may shorten the search, but it should not shorten the time spent thinking.
Does it keep its value after the first month?
The first-week appeal is clear, but the month-to-month value is more limited. This is not the kind of finance app I would open every morning. Its usefulness depends on whether I occasionally need to investigate a cash advance or personal loan offer. If my finances are stable, leaving it installed may not provide much recurring benefit.
That is not necessarily a weakness. Some apps are valuable because they are available when a specific situation arises. A roadside assistance app may sit unused until a breakdown; a borrowing app can occupy a similar role. The difference is that financial apps can influence long-term obligations, so I would keep it only if I expect to need this type of comparison again and trust myself not to browse offers impulsively.
The app has attracted an average rating of 4.7 from over 900 ratings, with more than 20 written reviews. That suggests a generally positive reception among people who chose to rate it, although ratings alone cannot tell me whether an offer was affordable, whether repayment went smoothly, or whether the experience remained useful months later. I treat the rating as a sign that the basic experience works for many users, not as proof that every financial outcome will be favorable.
Its install base is over 10,000, which gives it some real-world presence without making it feel like an unavoidable mainstream service. For me, that reinforces the need to judge the app on its process and suitability rather than popularity. A smaller finance app can still be useful, but I would be more deliberate about checking each screen and keeping copies of important information.
The best recurring use I can see is occasional comparison. If I face a genuine shortfall, I can return to the app, make a precise request, and compare the result with alternatives. The less useful pattern would be opening it every time I want something that is not essential. That turns an emergency tool into a way of normalizing repeated borrowing.
Who is likely to benefit
I think the app suits someone who wants a quick online starting point for researching short-term cash or personal loan possibilities and is prepared to compare the full repayment terms. It may also help a person who does not know where to begin and would rather investigate digitally than contact several providers one at a time.
It is less suitable for someone who needs guaranteed approval, immediate certainty, or a fixed borrowing cost before submitting a request. An offer-search app cannot remove eligibility decisions or make every request successful. I would also steer clear if the repayment date is already uncertain. If the only way to repay one loan is to take another, the app is not solving the underlying problem.
People who want long-term spending control should look elsewhere or pair this app with a budgeting method. It does not replace an emergency fund, a debt repayment plan, or a conversation with a lender about an existing difficulty. The most responsible role for it is narrow: explore a possible solution, understand the commitment, and stop using it once the decision is made.
The maintenance burden of keeping it installed
The practical maintenance burden appears modest, but financial maintenance is more important than technical maintenance. Keeping the application updated is sensible, especially because it is still on an early version. I would also remove it if I noticed that I was checking it without a specific need or feeling tempted by available borrowing rather than using it to address a defined expense.
Another useful habit is to keep a private record of any request and its outcome. I would not rely on the app as the only place where I remember repayment details. Saving the agreement through the appropriate official method and placing the due date in my calendar creates a second line of protection against missed obligations. The app can help start the process, but my own records should control the follow-through.
I would also review whether the app still has a place on my phone after an emergency passes. If I have no realistic reason to use it again, uninstalling it can be a healthy boundary. A finance tool does not need to remain permanently installed to have been useful. In fact, temporary installation may be the better choice for someone who wants to avoid making borrowing feel like a routine shopping option.
Where fatigue and frustration may appear
The main source of fatigue is the gap between a fast request and a careful decision. The app’s purpose naturally emphasizes speed, while responsible borrowing requires patience. Moving from a simple request screen to detailed terms can feel like a change of pace, particularly when someone is stressed. I would regard that slower stage as necessary rather than inconvenient.
Another possible frustration is uncertainty. A user may open the app hoping for a clear answer and instead need to work through eligibility information or compare an offer with alternatives. That is normal for borrowing, but it means the product may feel less satisfying than a standard shopping app. It is not designed to provide instant gratification, even if the initial interaction is quick.
I would also be cautious about repeated requests. Submitting applications casually can create confusion about what was requested and when, while multiple borrowing attempts may make personal finances harder to track. My concrete rule would be to prepare the amount and repayment plan first, then complete one considered review rather than experimenting with several amounts.
Finally, the app is not a substitute for human guidance when the situation is serious. If I were already behind on bills, juggling several debts, or unsure how much I could repay, I would seek independent financial advice or speak directly with the relevant provider before using another borrowing route. The app may be useful for a narrow need, but it should not become a way to postpone a larger financial conversation.
My long-term verdict
After the novelty fades, Cash Advance – Quick Borrow earns a limited but understandable place. I see it as an occasional research tool for people who want to explore cash advance and personal loan offers online. Its free installation, focused purpose, and positive average rating make it reasonable to consider when a real short-term need appears.
What keeps me from recommending it as a permanent everyday finance companion is the same focus that makes it useful. It helps with borrowing possibilities, not with building savings, controlling spending, or reducing dependence on credit. Its lasting value therefore depends on discipline. Used once, carefully, it may save time. Used repeatedly without a repayment plan, it could make financial pressure harder to escape.
My practical recommendation is to use it as a comparison step, never as an automatic borrowing button. Decide the smallest amount that solves the actual problem, inspect the total repayment obligation, compare alternatives, and record the final terms before accepting anything. If the numbers do not fit comfortably into the next budget, the right answer is to pause rather than force the request.
For someone with a specific emergency and enough certainty about repayment, I would consider installing it and reviewing what it offers. For someone seeking a permanent money-management system, I would choose a budgeting or banking tool instead. That distinction is important: this app can be useful at the edge of a financial problem, but it should not become the center of your financial life.
Frequently Asked Questions
What is Cash Advance – Quick Borrow, and how does it work?
Cash Advance – Quick Borrow is a financial app designed to help eligible users request short-term borrowing options through a mobile device. After creating an account, you may be asked to provide personal, employment, income, and banking information so the service can evaluate your request. Available amounts, approval decisions, repayment periods, and funding times can vary depending on your profile, location, and the app’s current lending partners.
Who can use Cash Advance – Quick Borrow, and what information is required?
Eligibility normally depends on factors such as your age, country or state of residence, regular income, an active bank account, and the provider’s internal requirements. During registration, the app may request identity details, contact information, employment or income data, and permission to verify your account. Requirements are not necessarily the same for every applicant, so review the eligibility conditions carefully before submitting an application.
How much does borrowing through the app cost?
The total cost may include interest, service charges, subscription fees, origination fees, late-payment charges, or other costs, depending on the offer you receive and the applicable provider. Do not rely only on advertising that mentions a quick advance or low fee. Before accepting, carefully check the annual percentage rate, finance charge, repayment amount, due date, and any automatic payment conditions shown in the agreement.
How quickly can I receive the money, and how is repayment handled?
Funding speed depends on approval, bank processing times, verification checks, weekends, holidays, and the financial institution receiving the transfer. Some users may receive funds quickly, while others may experience delays. Repayment is commonly made through a linked bank account or another supported method, and automatic withdrawals may be enabled. Confirm the exact due date and payment schedule so you can avoid unexpected fees or overdrafts.
Is Cash Advance – Quick Borrow safe to use, and what should I check before downloading?
Before using the app, verify that it is available legally in your location and identify the actual lender or financial provider behind each offer. Read the privacy policy to understand how your personal and banking data are collected, shared, and stored. Download only from an official app store, review permissions, examine recent user feedback, and avoid entering sensitive information if the terms, fees, company identity, or customer-support details are unclear.


